Financial Planning Strategies for Retirement in Times of Economic Uncertainty
Understanding the Importance of Strategic Financial Planning in Uncertain Economic Times
In today’s economic climate, marked by unpredictability and rapid change, the significance of strategic financial planning for retirement has become increasingly apparent. With varying economic indicators and the potential for financial downturns, individuals are urged to approach their retirement strategies with foresight and adaptability. The current landscape offers several hurdles that can profoundly impact long-term financial security, underscoring the necessity of a proactive approach tailored to individual circumstances.
Market Volatility
Market volatility is a significant factor that can greatly influence retirement savings. For instance, a sudden market downturn can decrease the value of equity investments, leading individuals to question the viability of their current retirement strategies. Historically, the stock market has experienced substantial fluctuations; in 2020, the COVID-19 pandemic caused unprecedented market drops. Retirees often rely on investments for income, and a decline in stock prices can directly reduce available funds. To mitigate these risks, it is vital to maintain a diversified investment portfolio that includes a mix of assets, such as stocks, bonds, and real estate, which can collectively reduce exposure to any single economic shock.
Inflation Rates
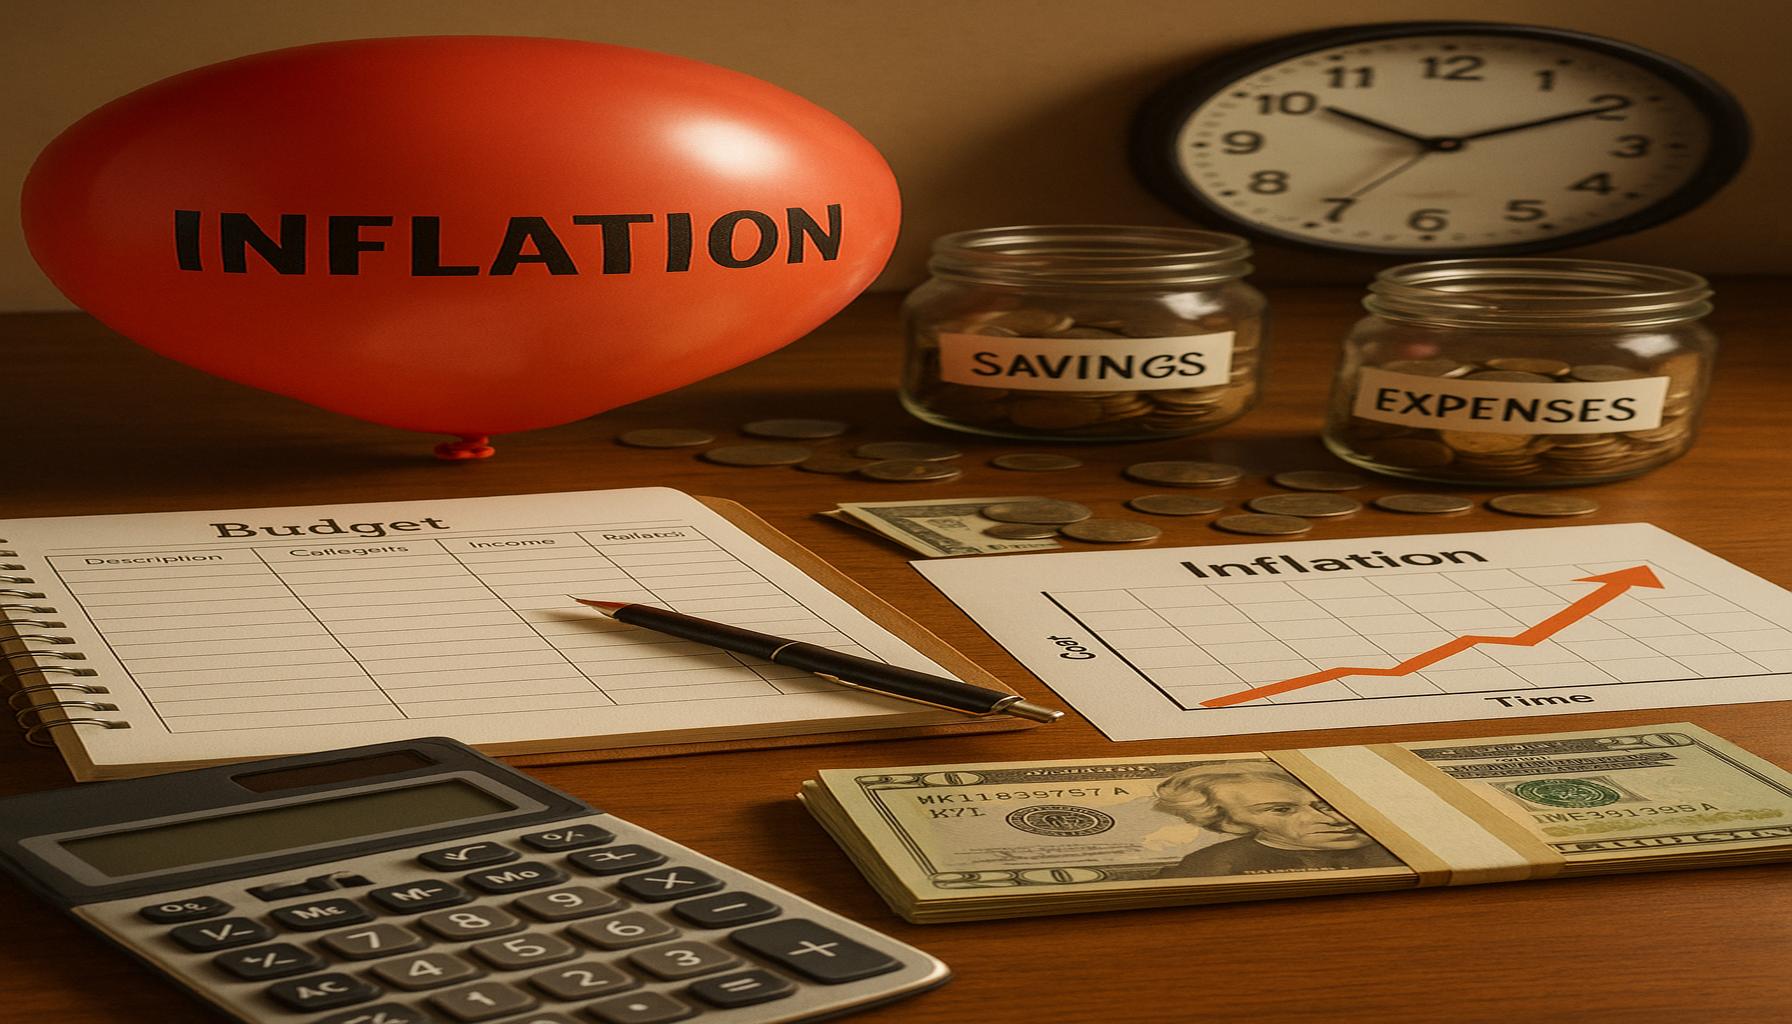
Inflation rates pose another crucial challenge, as rising costs can significantly erode purchasing power. For instance, if inflation rises at a higher rate than anticipated, retirees may find that their fixed retirement income is insufficient to cover essentials like healthcare, housing, and food. As of 2023, the U.S. has witnessed inflation rates fluctuating between 3% to 9%, prompting many individuals to reconsider their withdrawal strategies. To counteract these effects, incorporating a moderate level of growth investments in the retirement portfolio can help ensure that savings grow at least in line with or above inflation rates.
Interest Rates
Another vital aspect is the influence of interest rates on both investment returns and borrowing costs. As we have seen over recent years, central banks periodically adjust interest rates in response to economic conditions. For retirees relying on fixed-income investments, such as bonds, low interest rates can result in lower returns, making it even more critical to reassess asset allocations. For instance, during periods of low rates, it may be advantageous to explore options like dividend-paying stocks or real estate investment trusts (REITs) that can provide higher yields.
Implementing Robust Planning Strategies
In light of these economic challenges, adopting a comprehensive and robust planning approach is essential. Individuals should focus on creating a diversified investment portfolio that includes a variety of asset types to optimize returns while managing risk. Additionally, being vigilant about tracking expenses and seeking ways to reduce unnecessary expenditures can enhance financial flexibility. Lastly, making informed lifestyle choices—such as delaying retirement or considering part-time work—may offer additional financial stability during uncertain times.
By integrating these strategies, individuals can enhance their resilience against economic fluctuations and work towards ensuring a more secure retirement. Proactive financial planning is not merely an option; it is a necessity for anyone preparing for retirement in this increasingly unpredictable financial landscape.
Key Financial Considerations in Retirement Planning
When navigating the complexities of retirement planning during times of economic uncertainty, it is essential to identify and evaluate critical financial components that can influence long-term success. Several key considerations guide individuals in formulating effective strategies to safeguard their retirement savings and ensure financial stability. By understanding these components, individuals can equip themselves to withstand fluctuations in the economy and make informed decisions regarding their financial futures.
Establishing a Clear Financial Goal
One of the foundational elements of effective financial planning is establishing a clear financial goal. This goal should encompass not only the desired lifestyle in retirement but also the timeline for achieving it. It is crucial for individuals to assess their current financial situation, including assets, income sources, and liabilities, to develop a comprehensive retirement plan. This assessment allows individuals to set realistic savings targets and determine appropriate withdrawal strategies from retirement accounts.
Emergency Fund and Liquid Assets
Maintaining an emergency fund is another vital component of financial planning during uncertain times. Economic downturns can result in unexpected expenses, such as medical emergencies or property repairs, which may disrupt retirement plans. Experts recommend that retirees keep three to six months’ worth of living expenses in easily accessible liquid assets. This fund serves as a financial cushion, providing peace of mind and preventing individuals from having to liquidate long-term investments during unfavorable market conditions.
Investment Strategy and Risk Management
An effective investment strategy is fundamental to sustaining financial security throughout retirement. Considering current economic volatility, individuals should focus on risk management within their investment portfolios. Factors to include when constructing a well-balanced portfolio are:
- Diversification: Spreading investments across various asset classes and sectors to mitigate risk.
- Asset Allocation: Regularly adjusting the percentage of stocks, bonds, and other investments based on age and risk tolerance.
- Rebalancing: Periodically reviewing and rebalancing the portfolio to maintain desired risk levels.
- Tax Optimization: Understanding the tax implications of different investments to maximize after-tax returns.
By adopting an informed approach to investment strategy and risk management, retirees can better position themselves against market fluctuations while aiming for capital growth and income generation.
Social Security and Annuities
Lastly, understanding the role of Social Security and annuities in the retirement income landscape is crucial. Social Security benefits can serve as a cornerstone of retirement income; therefore, it is essential to assess the optimal timing to begin withdrawals. Delaying withdrawals can increase monthly benefits, but this decision should be weighed against individual health and financial needs. Additionally, incorporating annuities into a retirement strategy can provide a steady income stream, alleviating concerns about longevity risk—the risk of outliving one’s savings.
By focusing on these key financial considerations, individuals can cultivate a sound financial strategy that adapts to economic uncertainty, bolstering their resilience to market changes and ensuring a more secure retirement. Each element discussed requires careful thought and personalized adjustments based on individual circumstances to maximize potential outcomes in the face of an unpredictable landscape.
Enhancing Retirement Resilience Through Strategic Adjustments
In times of economic uncertainty, individuals must not only identify key financial considerations but also adapt their strategies proactively to enhance retirement resilience. This adaptability involves reassessing withdrawal rates, understanding market dynamics, and utilizing available financial instruments to mitigate risks associated with economic downturns. By refining these strategies, individuals can ensure that their retirement plans remain robust even amid fluctuating economic conditions.
Reevaluating Withdrawal Rates
One critical aspect of retirement planning is the withdrawal rate, which dictates how much of one’s savings can be safely drawn down each year. A commonly cited rule—the 4% rule—suggests that retirees withdraw 4% of their portfolio annually. However, this approach may need modification in times of economic uncertainty, especially if market downturns lead to significant portfolio depreciation. To safeguard their savings, individuals may consider a more conservative withdrawal approach of 3.5% or lower, thus extending the longevity of their retirement funds. Additionally, implementing a variable withdrawal strategy that adjusts based on market performance can help in preserving capital during downturns.
Market Timing and Economic Indicators
Understanding economic indicators and market timing can equip retirees with the knowledge necessary to navigate turbulent times. Factors such as inflation rates, interest rates, and unemployment figures serve as key indicators of potential economic performance. For instance, rising inflation can erode purchasing power, prompting retirees to consider investments that offer protection against inflation, such as Treasury Inflation-Protected Securities (TIPS) or commodities. Staying informed about these economic signals allows individuals to make timely adjustments to their investment portfolios, ensuring that they are not overly exposed to market volatility during downturns.
Utilizing Flexible Investment Vehicles
The choice of investment vehicles significantly influences the ability to weather economic storms. In uncertain times, incorporating flexible investment options such as exchange-traded funds (ETFs), mutual funds, or real estate investment trusts (REITs) can enhance portfolio diversification and liquidity. Furthermore, adopting a systematic investment strategy, like dollar-cost averaging, enables individuals to invest fixed amounts regularly, regardless of market conditions. This strategy reduces the impact of volatility and allows retirees to capitalize on lower prices during economic downturns.
Insurance Products as a Safety Net
Integrating insurance products into retirement planning can offer additional protection against financial risks. Long-term care insurance, for example, shields retirees from the potentially catastrophic costs associated with extended medical care. Similarly, incorporating life insurance products with living benefits can provide a source of liquidity and financial security in case of unexpected health-related expenses. By strategically employing insurance, individuals can establish a safety net that preserves their core retirement assets while addressing health-related uncertainties.
Ongoing Education and Professional Guidance
Finally, continuous education about financial markets and evolving economic conditions is essential for effective retirement planning. Engaging with financial advisors who specialize in retirement strategies can provide tailored insights and recommendations suited to individual financial situations. Professionals can offer valuable guidance on navigating complex financial instruments, market conditions, and personalized investment approaches, thereby enhancing individuals’ confidence in their financial decisions.
By reconsidering withdrawal strategies, closely monitoring economic indicators, utilizing flexible investment vehicles, and incorporating insurance products, individuals can bolster their financial planning for retirement. These adjustments not only promote resilience during economic uncertainty but also enhance overall financial security, ultimately leading to a more stable retirement experience.
Conclusion
In conclusion, navigating retirement planning during periods of economic uncertainty requires a strategic and multifaceted approach. By reevaluating withdrawal rates, individuals can adopt more conservative measures that prolong the sustainability of their retirement savings. Staying attuned to economic indicators is critical; understanding trends such as inflation and interest rates empowers retirees to make informed decisions, protecting their purchasing power and investment integrity.
Furthermore, leveraging flexible investment vehicles can significantly enhance portfolio resilience. Diversifying investments through ETFs, mutual funds, or REITs not only provides liquidity but also mitigates risks during market fluctuations. The incorporation of insurance products into retirement planning adds an essential layer of security, safeguarding against unforeseen health-related costs that could jeopardize financial stability.
Finally, the importance of ongoing education and seeking professional guidance cannot be overstated. Staying informed and collaborating with financial advisors who specialize in retirement can offer individuals tailored insights that align with their unique situations. By embracing these strategies, retirees can build a robust financial framework that withstands economic challenges, fostering a sense of security and stability during their retirement years. Ultimately, proactive financial planning not only ensures resilience in uncertain times but also paves the way for a fulfilling and secure retirement journey.